- What's at Stake: Non-QM borrowers and mortgage-backed securities investors face escalating risks.
- Expert Quote: "Nevertheless, modification performance continues to deteriorate." — dv01
- Forward Look: Watch for complicated delinquency cases and expect simpler ones to resolve.
Overview bullets generated by AI with editorial review.
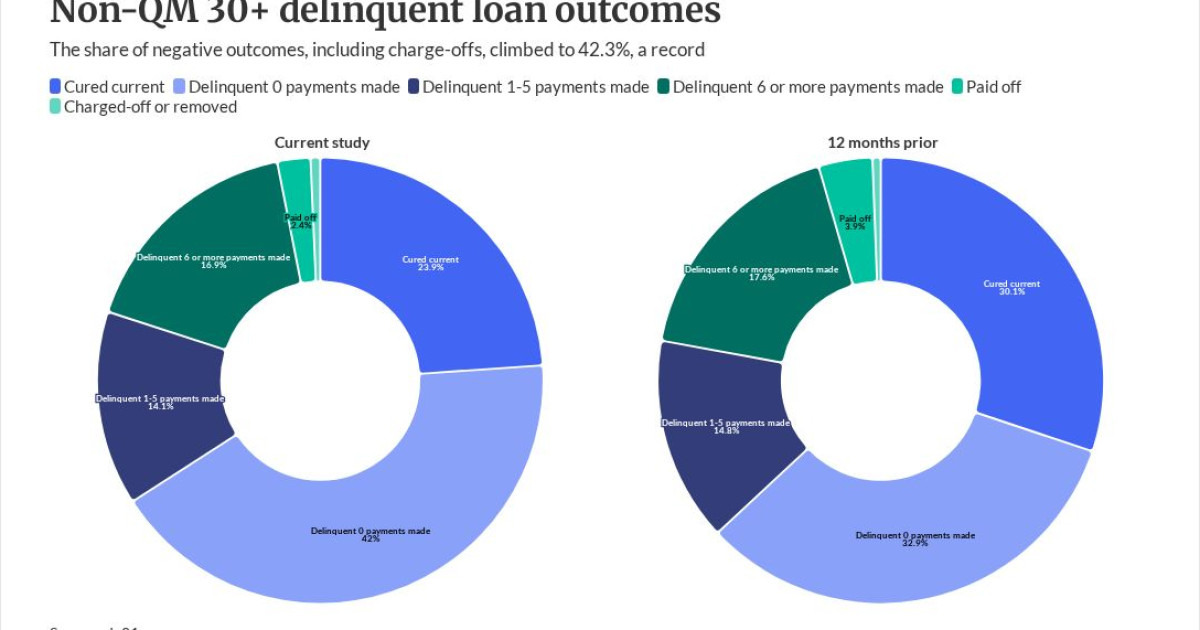
Distressed non-qualified mortgage loans are seeing weaker outcomes six months after they go delinquent, with negative ones at a new high point versus one year ago, a dv01 report said.
The report tracks delinquent and modified loan performance over a six-month time period for three asset classes; beside non-QM, it also covers consumer and subprime auto.
Dv01 said the long-term outcomes are more important than the shorter time frame data in analyzing the performance trends.
"Focusing on
"In today's market, borrowers rarely miss mortgage payments unless the situation is dire or the result of longer-term issues," dv01 added.
Negative outcomes for non-QM borrowers, defined as charge-offs or no payments made since the initial event, increased 9 percentage points from the prior year, to 42.3% versus 33.3%. This is a record high, dv01 said.
Meanwhile positive outcomes, where the mortgage becomes current, gets paid off or six or more payments have been made, still has a larger share at 43.2%. But a year ago, it was 51.6%.
Where the borrower is 90 days or longer late on their payments, the negative outcome is at 68.8%, over 10 percentage points higher than 58.7% 12 months ago, dv01 pointed out. Positive outcomes fell by a similar amount, to 30.8% from 41%.
"The deterioration in delinquency outcomes goes hand-in-hand with the overall impairment improvement seen over the past year," the report explained. "The major overall impairment improvement occurred in the second quarter of 2025, thereby improving outcomes from 12 months ago."
In its August update, dv01, a unit of Fitch, noted impairments are "trending sideways" in the past few months
"With
Mortgage-backed securities investors use
The outcomes for modified non-QM loans had what dv01 called "headline improvement," with the delinquency rate falling to 8.2% from 9.5% the prior year.
But the other outcomes it considered negative, including payment reduction or a new modification rose to 24.1% from 13.6%.
This increase is "slightly inflated" because interest-only loans (dv01 gave a caveat some of these were previously under stress but payment behavior could not be verified) fell to 7%, down from 11.7% during the comparative period.
"Nevertheless, modification performance continues to deteriorate," the report continued.
Borrowers
Factors like the gross weighted average coupon and the debt-to-income ratio "are critical as they limit repayment flexibility and signify a need for more severe resolutions," the dv01 report noted.
"This helps explain the increasing use of payment reduction modifications, which to date have been rare in the non-QM universe given the strong equity position and overall positive credit fundamentals," the report added.