
- Key Insight: Find out how lenders adjusted credit access as conforming mortgage rates rose in September.
- What's at Stake: Homebuyers and refinancers facing restricted access to key loan programs as lenders pull back.
- Expert Quote: "Growth in non-agency loan programs continues to support this segment." — Joel Kan, MBA Overview bullets generated by AI with editorial review.
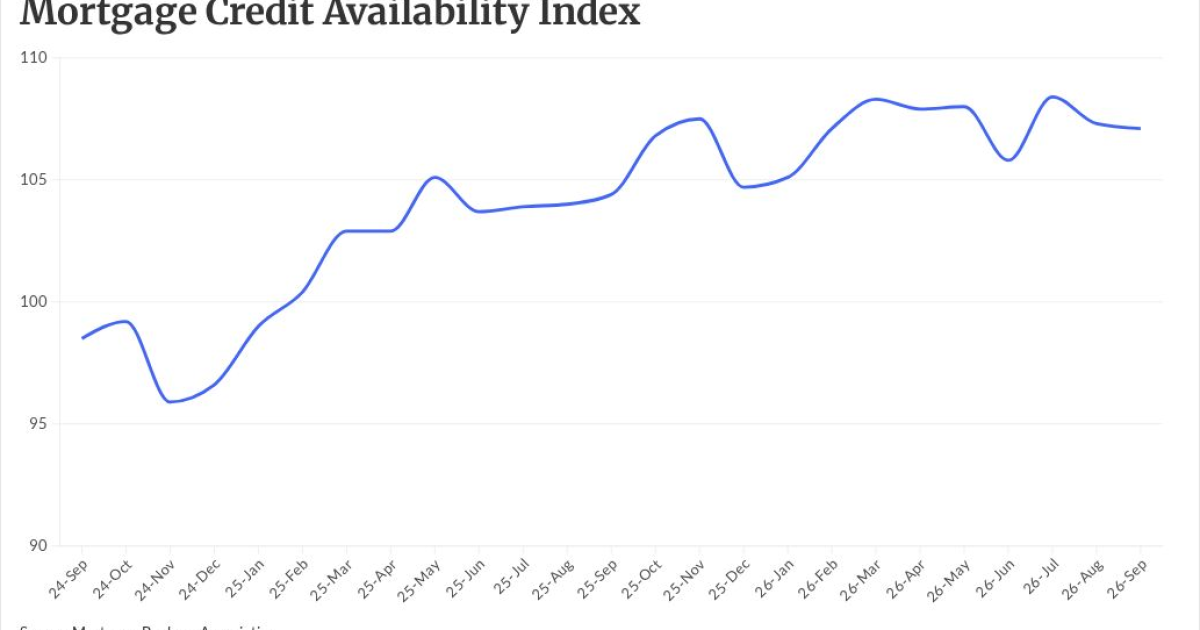
Mortgage program availability tightened in September, as conventional lenders reacted to an environment where conforming mortgage rates rose 64 basis points.
It is the fourth month out of the last six where lenders cut back on the type of credit they were extending to homebuyers and refinancers.
The Mortgage Bankers Association's Mortgage Credit Availability Index ended last month at 107.1, a 0.2% decline
The index baseline is 100, measuring credit availability in March 2012. Since February 2025, the MCAI has been higher than this level and over 104 since August of that year.
This month's change came entirely from the conventional component, with the conforming index down by 0.2% and the jumbo down 0.5%, even with a rate inversion.
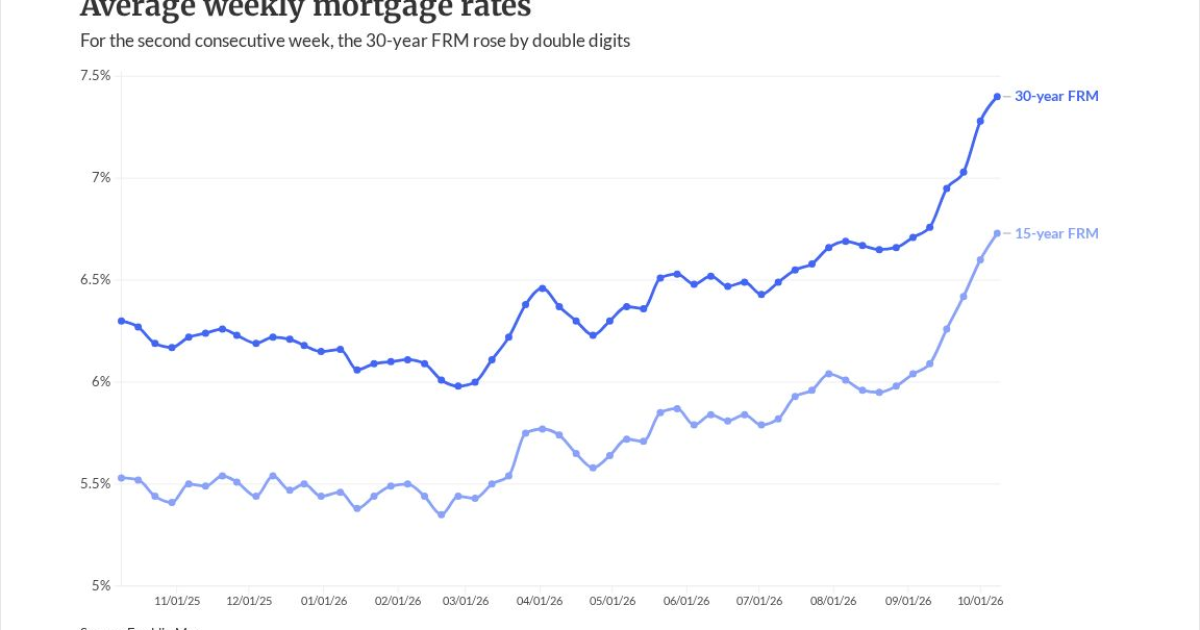
Rates on the conforming 30-year fixed were 7.49% the week ended Oct. 2 compared with 6.85% on Sept. 4, the MBA's Weekly Application Survey noted.
Jumbo program tightening occurred as its rate went to 7.39% at the end of September from 6.74%.
"Lenders tightened documentation requirements on conventional loans and reduced offerings of loans that allow for cash-out refinances and investor home purchases," said Joel Kan, the MBA's vice president and deputy chief economist in a press release. "However, recent growth in non-agency loan programs continues to support this segment of the market."
Adjustable-rate mortgage application volume was at 10.3%, unchanged from the prior week, the WAS reported. Rates on the 5/1 ARM declined to 6.43% from 6.47%.
Refinance applications declined 8% from the prior week; they were 56% lower from the same time in 2025. Purchases were just 2% lower week-to-week and down 15% compared with one year prior.
While securitization activity lags mortgage originations, September had just over $16 billion in priced residential mortgage-backed securities issuances according to Morningstar DBRS, citing CreditFlow data.
This was 86% of the 2026 monthly average of $21.4 billion. "still in context with the highest monthly volumes seen last year," the report said. "To close out Q3 2026, pricing volume totaled approximately $61 billion, the lowest quarter of the year so far, but not by much, as Q3 volume was higher than any quarter of 2025."
Prime jumbo was 17% and
"September's RMBS performance data reflects a market adjusting to
Delinquencies were higher and prepayment speeds continued to slow.
"Despite those pressures, deal structures remained largely stable, credit losses stayed low, and credit enhancement levels continued to improve," Fontanilla said. "At the same time, issuance activity remained robust, with year-to-date RMBS volume already surpassing last year's full-year total and reaching a post-Global Financial Crisis record."