
- Key Insight: The real reason Zillow is launching interest-free second loans for FHA buyers.
- What's at Stake: Whether assisted buyers will lose their homes to unbudgeted insurance and maintenance costs.
Overview bullets generated by AI with editorial review.
The availability of financial assistance for aspiring homeowners is at an all-time high, as
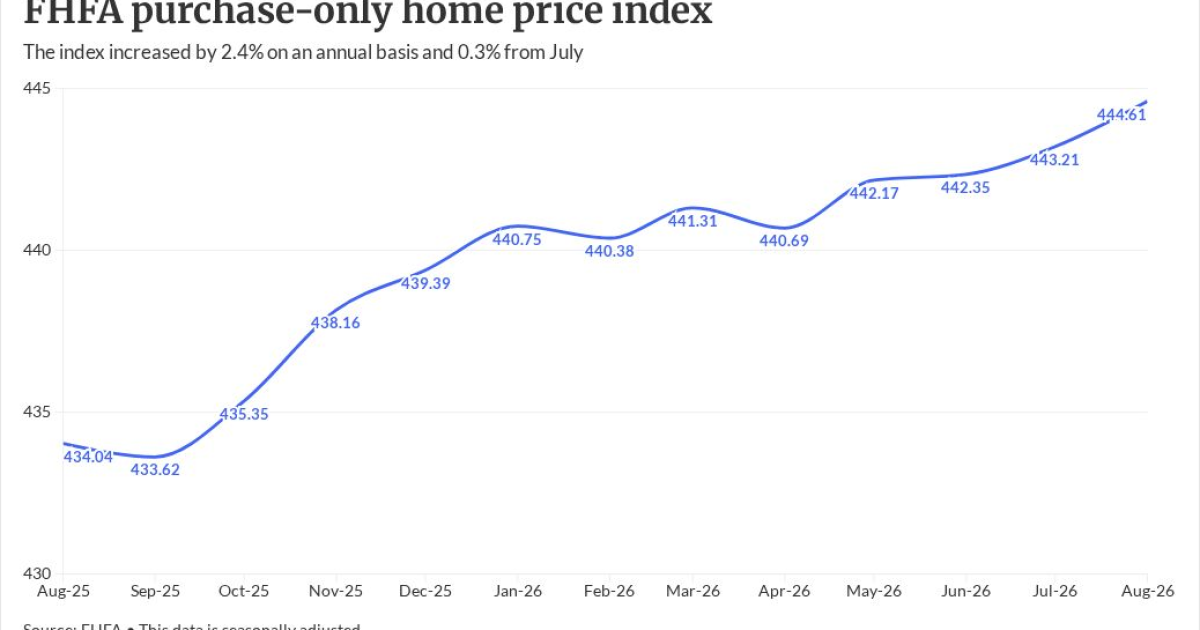
Meanwhile, as the recent Federal Housing Finance Agency and S&P Cotality Case-Shiller home price indices reports note,
Zillow, looking to address affordability from the down payment standpoint, is the latest lender to bring a program designed to eat up some of the gap between what the borrower has and what is needed for mortgage underwriting purposes.
Down Payment Resources' third quarter Homeownership Program Index reported 2,833 offerings nationwide, a gain of 87 or 3.2% from the second quarter. The measurement includes both down payment assistance and grant programs.
"Quarter after quarter,
How Zillow's program works
Zillow Home Loans has launched a
The funding is structured as a second loan with no interest and no payment. It does not require the purchaser to be a first-time buyer and will be forgiven if the borrower makes five years of on-time payments on their primary mortgage loan.
Buyers and real estate agents are telling Zillow getting the down payment is the problem.
"This program helps us serve more qualified buyers by giving them a simple way to clear that hurdle, with their mortgage and down payment assistance handled in one place," said Eric Wilson, Zillow's senior vice president and general manager of mortgages, in a press release. "For buyers who can afford the monthly payment, we can now cover the full minimum down payment."
Helping Arizona Realtors close deals
Down Payment Resource does not have an exact count on how many lenders might directly offer these programs; it gets its data through its partners.
But plenty of originators have their own proprietary programs which offer various benefits, it said.
Meanwhile, DPR has recently entered into an agreement with the Arizona Regional Multiple Listing Service to give subscribers access to Down Payment Connect, a database it provides.
In the state, 34 agencies and 61 programs offer down payment assistance with an average assistance amount of $28,000. Programs are available to buyers earning up to $155,000 a year, purchasing homes priced up to $484,350, DPR said.
Do buyers need more to stay in their homes beyond DPA?
While not speaking specifically about the Zillow or any other program, having such assistance available gets a family to the closing table, said Alan Atchley, the owner of Better Homes and Gardens Real Estate Atchley Properties. But this is only part of the equation.
"What keeps them in the house is something else entirely," Atchley said. "I've walked buyers through starter homes where the down payment gap was solved and the roof had four years left in it, and nobody had budgeted for that."
In his home state of Florida, the homeowners insurance premium can change the borrower's payment more than a quarter-point shift in the mortgage rate can.
"Counseling that stops at the mortgage leaves the hardest part untouched," Atchley said. The buyers who hold on are the ones who priced the taxes, the premium and the deferred maintenance before they signed."
How long do renters have to save to buy a home?
The Julian Bond Institute at the Center for Responsible Lending said the number of years needed to save to buy a home for a median income family of renters was now 16 years, up from eight in the 2019 study.
A Black family needs 21 years to save to cover upfront costs, while a middle-income family needs 12 years.
"Families saving for homeownership have a far steeper climb than just a few years ago. Aspiring homeowners are living the harsh reality of the affordability crisis, especially if they can't get money for upfront costs from the 'bank of mom and dad,'" said Mike Calhoun, president of CRL and report co-author, in a press release.
"Alongside measures to expand the supply of starter homes and other housing, there is an urgent need for policymakers to expand down payment assistance programs for aspiring first-time homebuyers, especially first-generation home buyers."
Which other lenders offer down payment help
Zillow Home Loans joins the list of lenders with programs in place, both bank and nonbank.
"
B of A launched this program in 2019 and it has delivered $15 billion in affordable home loans in addition to over $600 million of down payment and closing cost grants, helping more than 57,000 homebuyers achieve homeownership, Vernon pointed out.
Earlier this year, the bank announced the program would continue as an ongoing commitment.
Others, both in third party and retail, have come out with offerings.
This past August, JPMorgan Chase announced
A year ago, Click n' Close, a company which specializes in providing down payment assistance offerings,
This takes an adjustable rate first, combined with a repayable second lien.
Total Mortgage has brought its closing cost assistance program, Lease to Keys, to market. It provides up to $2,500 to first-time buyers.
Last September, Texas lender SWBC Mortgage, provided an update on its Homeownership Expansion Loan Program, or HELP. Since its launch, it has done $2.3 million in DPA for 487 home loans nationwide.
Meanwhile, last summer, United Wholesale Mortgage
While not financial assistance, SimplyPMG has brought out the First-Time Homebuyer Dilemma, a tool to answer five questions from a consumer and then create two paths: Buy home now/invest later or keep renting/invest now.
"Everybody has an opinion on whether you should buy or keep renting, and most of that advice was built for somebody else," said Jason Madiedo, CEO of SimplyPMG, said in a press release. "What matters is what the numbers say for you, everyone's situation might be different. We built something free and simple so people can see that for themselves."