
- What's at Stake: Title underwriters risk losing refinance transaction volume to a newly expanded federal waiver program.
- Expert Quote: "So what comes out of that, we just don't know yet." — Mike Nolan, CEO, Fidelity National Financial Overview bullets generated by AI with editorial review.
Title company earnings going forward could be affected by the expansion of a secondary market pilot program to reduce the cost of this coverage to consumers. But the early comments from industry executives showed little concern.
The current iteration is limited to certain loan types, regions and lenders and thus has not had a big impact on title company business.
But the
During Fidelity National Financial's earnings call on Nov. 6, which was prior to the Pulte post, Mike Nolan, CEO said in response to an analyst's question, "it was too early to tell because really all the executive order did was direct the director to think about things. So what comes out of that, we just don't know yet."
Later in the call, Nolan cited a National Mortgage News article, which said the government-sponsored enterprises had handled 22,000 waiver transactions to date, which he said was over a two-year period.
He pointed out over 3 million residential refinances took place during this time frame.
"I would also just say anecdotally, I still do not have anyone in our world here at the FNF family of companies really telling me they're losing orders to the waiver program," Nolan said.
On its call, Stewart Information Services CEO Fred Eppinger called the waiver program "old news." The call took place prior to the executive order announcement, although the questioner noted rumors of a potential expansion.
"We are not really big in the refi market and I don't think there's many that want to be big in the refi market given the volatility of that business and the low margins that are in it," Eppinger said.
On the calls, the continued elevated mortgage rate environment was a common theme, but for some, commercial business was an offset. All four of the large underwriters also noted their investments in artificial intelligence technology to re-engineer processes.
Here are the highlights of each company's results for the third quarter:
Analyst raises Fidelity National estimates
Keefe, Bruyette & Woods analyst Bose George increased his fourth quarter 2026 and full year 2027 earnings estimates on Fidelity National Financial after the earnings call.
"Our higher near-term estimates are primarily on higher investment income and FG income, offset by weaker volume trends (which also negatively impact 2028)," George said.
FG is the ticker symbol for F&G Annuities and Life, of which FNF is the majority owner.
During the third quarter, FNF had net earnings attributable to common shareholders of $633 million. This
"Over the course of the year, purchase orders opened have held up well through August with each month comparing favorably to the prior year before falling behind by 2% for the month of September," Nolan said. "Importantly, we continue to steadily outperform relative to our peers."
On the residential side, daily purchased orders opened were up 3% year-over-year, while daily refinance orders fell 11%. But commercial orders opened, which commands higher fees, increased 2%.
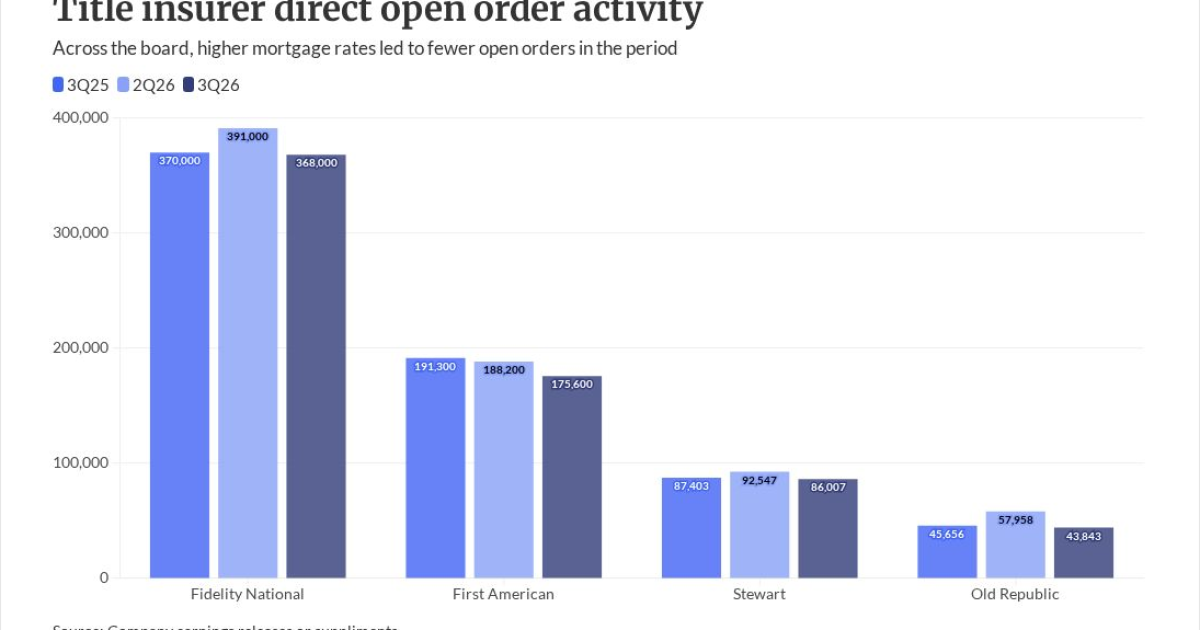
Total opened orders ended the quarter at 368,000, versus 391,000 three months prior and 370,000 one year before.
Data centers,
"Similar to energy, data centers tend to be higher premium transactions, although comprising a small portion of the overall order count," Nolan said. "This shows up in our national fee per file, which benefits from the larger energy and data center deals."
Data centers driver of First American's commercial strength
First American Financial noted that of its 22 commercial closed transactions during the quarter, six were for data centers.
This shows "a broader strength to the market that includes energy, industrial and multifamily," CEO Mark Seaton said on the earnings call.
First American reported net income of $177 million during the quarter, compared with $218 million in the second quarter and
George dropped his earnings per share estimates, pointing to management guidance for flat revenues and fairly flat title insurance margins. This led him to reduce his stock price target to $79 per share from $82.
"We expect the recent trend of a strong commercial market and a sluggish residential market to continue," Seaton said about the company's outlook through 2027. "For the first three weeks of October, our open purchase orders are down 8%, and refinance is down 35% and commercial is down 7%."
Still, after looking at its pipeline of commercial orders, First American believes this segment will have a strong finish in 2026.
Seaton expects these trends to continue next year.
First American finished the third quarter with 175,600 open orders. This compared with 188,200 in the second quarter and 191,300 for the year ago period.
Weaker trends to affect Stewart's earnings
Citing "weaker macro trends" at Stewart Information Service, George reduced his earnings per share estimates and stock price target here as well.
But Eppinger said he was "feeling pretty bullish on our AI initiatives. I think the financial impact is going to take 18 months to kind of see the robust financial impact, although we are seeing it today, particularly in the search area."
Business-wise, the outlook isn't positive.
"We believe the residential market conditions will continue to decline into the next quarter," said Eppinger. "Considering this outlook, we will be very focused on managing our business investments and expenses while continuing to capitalize on some of the market opportunities this disruptive market will create."
Stewart still is
It reported net income of $30.3 million for the most recent period. This compared with $37.2 million in the second quarter and $44.3 million for the third quarter of 2025.
The company ended with 86,007 open orders, down from 92,572 for the second quarter. One year ago, it did 87,403.
Old Republic: 'Solid results' but uncertainty ahead
Old Republic International's title insurance unit reported a 10% increase year-over-year in pretax operating income, to $50.4 million from $45.7 million.
Net income at the parent company, which has a significant specialty insurance underwriting business, totaled $243.2 million, compared with $279.5 million in the second quarter last year.
"While title continued to produce solid results, the recent increase in mortgage interest rates does create some uncertainty regarding transaction volumes as we go forward," said Craig Smiddy, president and CEO of the holding company on the earnings call. "But we think our title business has demonstrated over many decades an ability to remain profitable and adapt through a variety of housing and mortgage rate environments."
Meanwhile, the shift to more of an agent-driven business model continued, with 81% of title revenues coming from premiums generated from this source, versus 80% one-year prior, said Carolyn Monroe, the title unit's president and CEO.
"As we move into the final quarter of 2026, we remain focused on improving operational efficiency and expanding our margins," Monroe said. "A key part of that effort is our partnership with Qualia and the continued rollout of our new operating system. Implementation began earlier this year and will continue through the end of next year, strengthening our foundation for long-term success."
In 2025, Old Republic
The segment had 43,843 open orders during the third quarter. This was down from 57,958 in the second quarter and 45,656 one year prior.
Net premiums written by Investors Title up 21% year-over-year
Revenues at Investors Title grew over 12% during the second quarter versus 2025, due to growth in premiums and related fees.
Meanwhile, net premiums written along with escrow and other title-related fees increased by more than 21%, reflecting higher real estate transaction volumes and contributions from ongoing expansion initiatives.
The company reported net income of $9.4 million, versus $14.6 million in the second quarter and $12.2 million one year ago.
But net investment losses of $1.7 million cut into the $81.9 million of revenue reported for the period.
Operating expenses also increased in the quarter versus one year prior, by nearly 22%, due to higher agent commissions, claim provisions and personnel expenses.
"We are pleased with the growth in title insurance revenues and continued ongoing initiatives," said J. Allen Fine, chairman, in a press release. "While higher claims experience and investment-related volatility decreased quarterly earnings, our underlying business continued to perform well, contributing to solid year-to-date results."