
- Key Insight: Here's why analysts downgraded UWM Holdings' stock rating and reduced industry estimates ahead of third-quarter earnings.
- What's at Stake: Whether brokers and borrowers will benefit from UWM's elimination of minimum credit score requirements.
- Expert Quote: "UWMC is 'cheap,' and the Street is overweight," — Kyle Joseph, StephensOverview bullets generated by AI with editorial review.
UWM Holdings, the parent company of United Wholesale Mortgage, had its stock rating downgraded by Keefe, Bruyette & Woods to market perform, with limited upside to its current price.
Meanwhile, UWM announced it will pull both FICO and VantageScore on every credit check and automatically use whichever is higher. A day later, it went further and eliminated minimum credit scores on Fannie Mae, Freddie Mac and Ginnie Mae loans, so automated underwriting now decides eligibility. Scores will still be used for pricing.
The stock rating downgrade was included in KBW's third quarter mortgage operating company earnings preview. The report from Bose George, Frankie Lebetti and Graham Bundy noted they were cutting their earnings per share estimates and price targets for mortgage originators, as well as
Why KBW dropped its ratings on UWM
But for UWM specifically, George dropped his price target to $1.50 per share from $2.75 per share.
"While we still forecast that the company would have the ability to
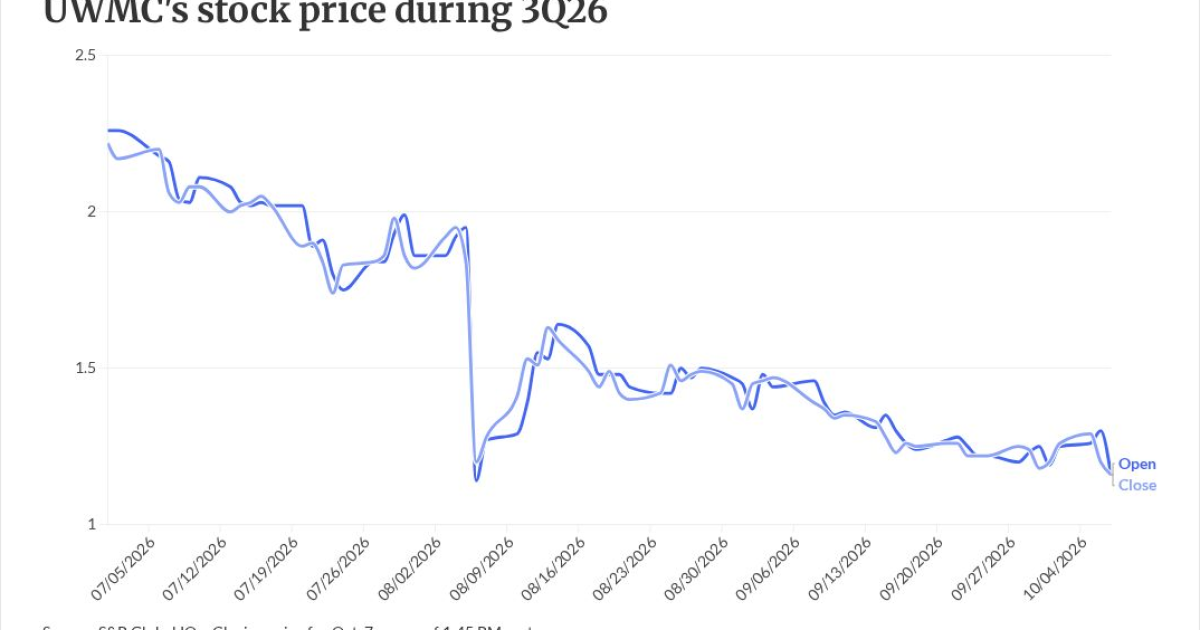
UWM's stock price has been generally declining since its
While it did hit $6.15 per share on Jan. 16, as the bidding war with CrossCountry heated up, the price tanked. On July 30, the day's high was $2.
The day KBW put out the earnings preview, Oct. 7, UWM opened at $1.16 per share.
UWM starts rights offering
Meanwhile,
The price target reduction reflects KBW's reduction of 2030 earnings to 30 cents per share from 49 cents, "to better reflect the company's cost of funds as it would likely replace some of the Oaktree Preferred with other debt. We're also using a higher discount rate (17% up from 12%) to better incorporate the higher cost of funds."
In a connected move, on Oct. 5, UWM launched a $400 million rights offering, a Securities and Exchange Commission filing said. This allows current stockholders to have the right to purchase 0.57 shares of Class A stock for each share currently owned.
It is priced at the greater of $2 per share or 85% of the volume weighted average price over a 10-day period ending three days before the offer expires on Nov. 12.
Industry third quarter earnings expectations from analysts
For the current quarter, George is expecting earnings per share of 2 cents from UWM, down from 4 cents and 10 cents for the full year, versus 13 cents.
He also
Pennymac was previously reduced to $1.10 for the quarter and $6.20 for the full year.
Onity was reduced 2 cents to $1.48 for the quarter, while Rithm was also unchanged.
Stephens analyst Kyle Joseph expects the focus of UWM's third quarter results to be the "go-forward strategy to scale its in-house servicing business in a game of catch-up."
He likes UWM's originations business. However, "it remains cyclical, and in recent years, the company has opportunistically sold MSRs thus shifting earnings even more towards originations. We remain on the sidelines following the recent capital raise/rights offering."
Stephens has UWMC stock rated as equal-weight. "UWMC is 'cheap,' and the Street is overweight," Joseph said. "We expect it to remain cheap until it cracks the cyclicality conundrum."
In general, with
"The good news: we know exactly what rates have done, and entering earnings, we balance these movements, late July/early August outlooks and subsequent updates from September conferences," Joseph wrote in his analysis. "While we are not anticipating strong quarters, we believe those that can post decent numbers will be substantially rewarded and have the most faith in Rocket doing so."
Besides Rocket and UWM, Joseph covers PennyMac Financial Services and Walker & Dunlop.
UWM to use model that returns best score
Separately, UWM formally announced a system enhancement which would automatically select the best credit score returned for a consumer.
The company as of September was the only other conforming mortgage seller besides Rocket to significantly use VantageScore 4.0. Recently, the nation's No. 3 originator,
Starting Oct. 1, Rocket made VantageScore its primary model, following the Federal Housing Finance Administration's equalization of the loan level pricing adjustment grids.
Talk abounds that FHFA Director Bill Pulte will announce a shift to a bi-merge pull from the current tri-merge at the Mortgage Bankers Association's annual convention next week.
"Our goal is simple: put borrowers in the best possible position while making it easier for brokers to do business," said Mat Ishbia, president and CEO of UWM in a press release. "No one should have to worry about which credit model wins. We handle that automatically by obtaining FICO and Vantage on all credit pulls to help consumers save more money and improve affordability, empowering brokers to close more loans."
FICO's comments
FICO put out its own press release the afternoon of Oct. 6 stating UWM reaffirmed its commitment to using its models on all credit pulls.
It used a similar quote from Ishbia in its press release.
"Our work with UWM is driven by our shared commitment to helping more consumers achieve the dream of homeownership," said Julie May, vice president and general manager of B2B FICO Scores. "We applaud UWM's continued commitment to using best-in-class risk assessment tools that help borrowers access competitive mortgage terms while supporting a strong and stable mortgage ecosystem."
UWM minimum score requirements on GSE and government loans eliminated
In an Oct. 7 announcement, UWM said it was removing minimum credit score requirements on Fannie Mae, Freddie Mac and Ginnie Mae mortgages effective immediately. Borrower loan eligibility will be determined through the automated underwriting system.
Scores can vary between models for the same borrower, which is why UWM decided to focus on the overall AUS decision, its press release said.
Credit scores will still be used for pricing purposes, for example, the LLPAs.
"Over the last year, we've taken a deep dive into the relationship between credit scores, borrower approvals and loan performance," Ishbia said. "What we found is that while credit scores are an important indicator, they are not the strongest predictor of a borrower's ability to qualify."
The AUS, on the other hand, delivers a much more complete assessment of the borrower because it evaluates numerous factors, he continued.
UWM is keeping minimum credit scores in place for non-agency products like jumbos, bank statement mortgages and Investor Flex loans.