
- Key Insight: The outcomes Newrez expects to see through expansion of its partnerships with artificial intelligence platforms.
- What's at Stake: Whether mortgage lenders can offset plummeting loan volumes by cutting operational costs.
Overview bullets generated by AI with editorial review.
Newrez executives put a number on the expected savings to come from artificial intelligence investments, at the same time that interest rates are likely to cut into new production volume across the mortgage industry.
Following multiple
"Most likely you'll start to see them kick in in '27, but it'll go on for '27, '28," said Michael Nierenberg, CEO of Newrez parent company Rithm Capital, about when tangible financial benefits would appear on the bottom line.
"The partnership with Valon should be extremely significant across our entire business as we go forward, and it's not only Valon, but others," he continued in Rithm's third-quarter earnings call, referring to the servicing technology platform the asset management firm
The technology investments will serve as a key differentiating factor for Newrez's lending operations, said unit President Baron Silverstein, who described AI's impact on a business as "remarkable."
"We think this is one of the top components of how we can continue to drive performance," he said.
Newrez's performance in Q3
The boost in AI investment comes amid a slowing mortgage lending landscape in 2026, with the company
The mortgage subsidiary of Rithm Capital found reason to celebrate despite the latest challenges, posting third-quarter pre-tax profits of $604.8 million. The number included a favorable upturn in the fair value of mortgage servicing rights of $121.3 million.
The latest quarterly income increased 435%
Newrez profit came on the back of $1.2 billion in revenue, representing a 71.2% increase from the prior quarter's $704.2 million and a year-over-year boost of 44.2% from $836.2 million.
The impact of
A surge in rates over the past month had leaders warning of subdued originations activity for the near term.
"We've seen a pretty material decline in production coming from September to October," Silverstein said. A fall in volume is likely to approach 25%, he added.
A bright spot emerged in non-agency originations, though, with much of the industry looking at outside conventional and government products to generate business. Non-agency volumes increased by approximately 8% quarter to quarter and 30% from one year ago, with Rithm noting the upside non-qualified mortgages have for its asset management business.
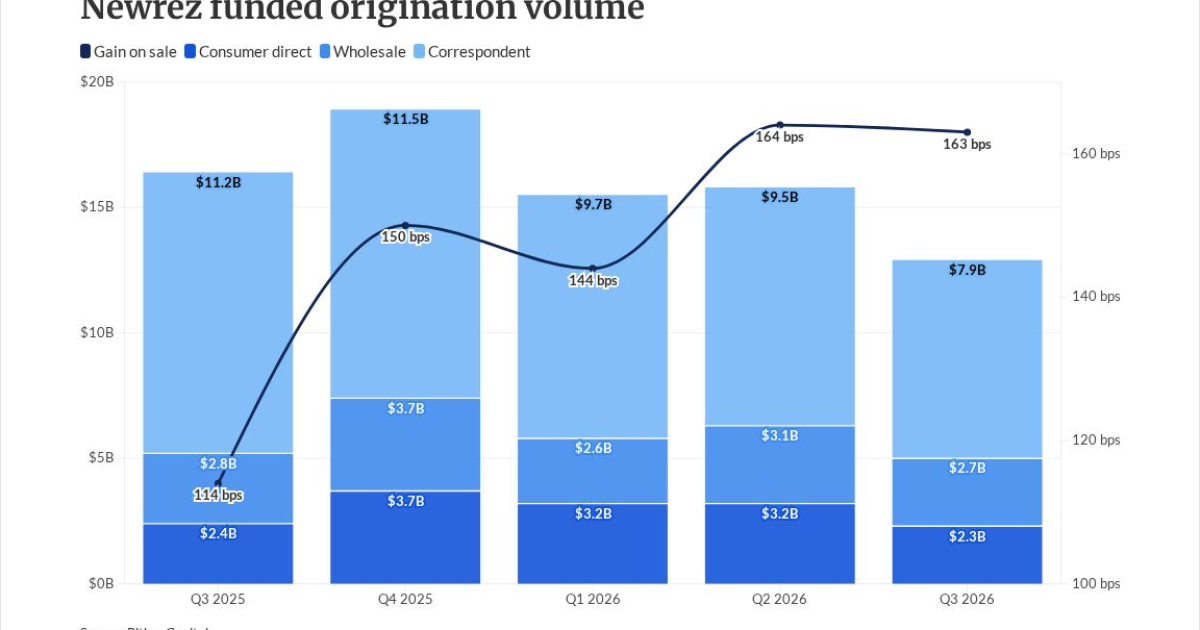
Meanwhile, gain-on-sale margins on new originations were largely on par with the second quarter, decreasing to 163 basis points from 164. Consumer-direct loans boosted margins, with the channel posting gain on sale of 566 basis points.
On the servicing side, unpaid loan balances stood at $878.9 billion, rising from $865.2 billion in the second quarter and $864.2 billion 12 months earlier. Third-party servicing contributed $28 billion to the quarterly balance, up by approximately 5%, Newrez reported. The company has added 15 new subservicing customers this year.
The originations segment provided $71 million of income to Rithm's third-quarter bottom line, while upward rate movements led the servicing segment to $306.3 million of pre-tax profit. The same second-quarter totals came in at $105 million and $254.6 million, respectively.
Rithm Capital's results
Across all lines of business, New York-based Rithm reported a profit of $217.1 million based on generally accepted accounting principles, with the total surging from $20.2 million in the second quarter.
The bottom line outperformed the average consensus estimate of analysts surveyed by S&P Global, who had predicted $154.4 million in net income.
"The forward momentum of the business is tied to likely gains in operating efficiency at Newrez related in part to the adoption of a new platform and the growth of its asset management, commercial real estate and credit origination platforms," wrote Wedbush equity research analyst Henry Coffey in a post-call note.