
- Key Insight: See why UWM Holdings plans to unload up to $80 billion in mortgage servicing rights.
- Supporting Data: A 124 basis point margin on third-quarter loan originations.
UWM Holdings will be selling $70 billion to $80 billion of mortgage servicing rights and will join the proceeds with those expected from its stock rights offering to pay down debt.The sale is expected to bring in $1.8 billion, with the rights offering going as planned will add another $400 million of gross proceeds.
The company announced the sale in a preliminary third quarter earnings announcement put out as the
Stock analysts support MSR sales
"These sales will bring the MSR portfolio down to $210-230 billion unpaid principal balance by year-end versus our $262 billion estimate," BTIG analyst Doug Harter wrote in a note after the UWM release. "We view the sale favorably as UWMC looks to manage its leverage and ultimately pay back the preferred."
Leverage was
Keefe, Bruyette & Woods also celebrated the anticipated MSR sale, with Bose George calling it "a big positive." The announcement should also remove any market concerns about UWM's ability to sell its servicing rights.
The expected proceeds suggested the MSRs to be sold have a valuation of 240 basis points, George said. "This is above the estimated MSR carrying value of 214 basis points at the end of second quarter, which is also a positive sign but valuations of the sold MSRs might be higher or lower than overall valuation," he continued.
Preliminary net non-funding leverage of 1.75 times to 1.8 times on $2.8 billion of preferred and common equity implies UWM has approximately $4.9 billion to $5 billion of net non-funding debt before the planned transactions, George calculated.
Why UWM is making the common stock rights offering
A large hedge-related loss in the second quarter forced the company to raise capital from Oaktree Capital and an Ishbia-family controlled entity. The rights offering was announced as part of the capital raise.
At the end of the third quarter, UWM held approximately $270 billion of MSRs with a weighted average coupon of approximately 5.97% and weighted average servicing fee of approximately 40 basis points, the preliminary earnings said.
UWM Holdings is expecting third quarter net income between $205 million and $220 million.
In the second quarter, including the mark-to-market impact of the hedge, it had a GAAP net loss of $451.9 million. In the
"In aggregate, adjusted earnings were $3 million lower than our estimate," Harter wrote. "Weaker origination revenues (both volume and GOS margin) were not fully offset by better servicing revenue and lower operating expenses."
Third quarter volume at UWM
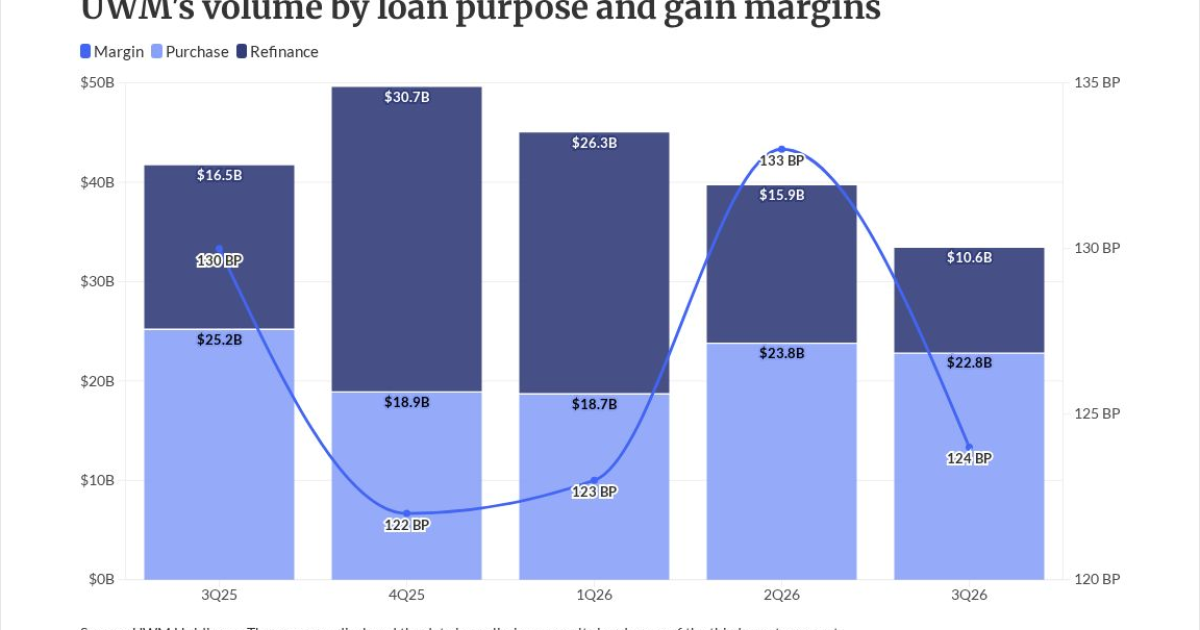
United Wholesale Mortgage ended the period with loan origination volume of $33.4 billion, including $22.8 billion of purchase and $10.6 billion of refinance originations at 124 basis point margin.
Second quarter production was $39.7 billion with gain-on-sale of 133 basis points. For last year's third quarter, volume was $41.7 billion with GOS of 130 basis points.
"While net income is well above us, other metrics are closer, which suggests that some of the upside was driven by higher MSR marks," George said.
He would later elaborate in his note "Since most metrics are not meaningfully different from us, we think MSR valuation gains (including hedges) likely drove some of the strong performance in net income."
How UWM's servicing portfolio performed
The preliminary earnings, which are subject to change, gives UWM servicing income between $240 million to $250 million and production income between $410 million to $420 million.
"We view these results as solid given the challenging rate environment," Harter said.
The servicing income beats George's expectations of $225 million and Harter's $233 million.
But on the origination side, George predicted $471 million; Harter said the number will come in between 7% and 10% lower than BTIG's estimates.
United Wholesale Mortgage expects it will hold an 8% market share in originations by year-end. Its servicing portfolio on Dec. 31 will be between $210 billion and $230 billion.
Total revenue for the year will be approximately $3.35 billion to $3.50 billion, which the company admitted will be lower than expected earlier in 2026 as a result of the mortgage industry as a whole producing fewer loans.
The stock market reacted positively, driving UWM's common stock price up 11 cents from its previous close, to $1,26 per share midday Friday.