
- Key Insight: The reason analysts cut Rocket's estimates stems from management's own downbeat internal projections.
- What's at Stake: PennyMac's path to a double-digit return on equity as macroeconomic headwinds mount. Overview bullets generated by AI with editorial review.
While Rocket's third quarter earnings beat analyst estimates, the dire industry forecast management gave has led a pair of stock analysts to drop their forward estimates on the company.Meanwhile, at PennyMac Financial Services, which also released results on Thursday, it too saw the earnings outlook lowered, plus Keefe, Bruyette & Woods downgraded its stock.
On the earnings call, Rocket management said
Management also adjusted Rocket's guidance, although as the KBW report from Bose George noted, the fourth quarter outlook assumes continued market share gains. In the third quarter Rocket grew purchase by 0.3 percentage points to 6.5%, while refinance increased to 15.5% versus 14.3% in the second quarter.
KBW's reasons for changing Rocket's forecast
"[Rocket's] Management reiterated confidence in its longer-term targets of 8% purchase and 20% refinance share," George said. "We estimate purchase and refinance share of 7.1% and 15.4%, respectively, for full-year 2027, leaving potential upside if the combined platform delivers faster gains than we currently assume."
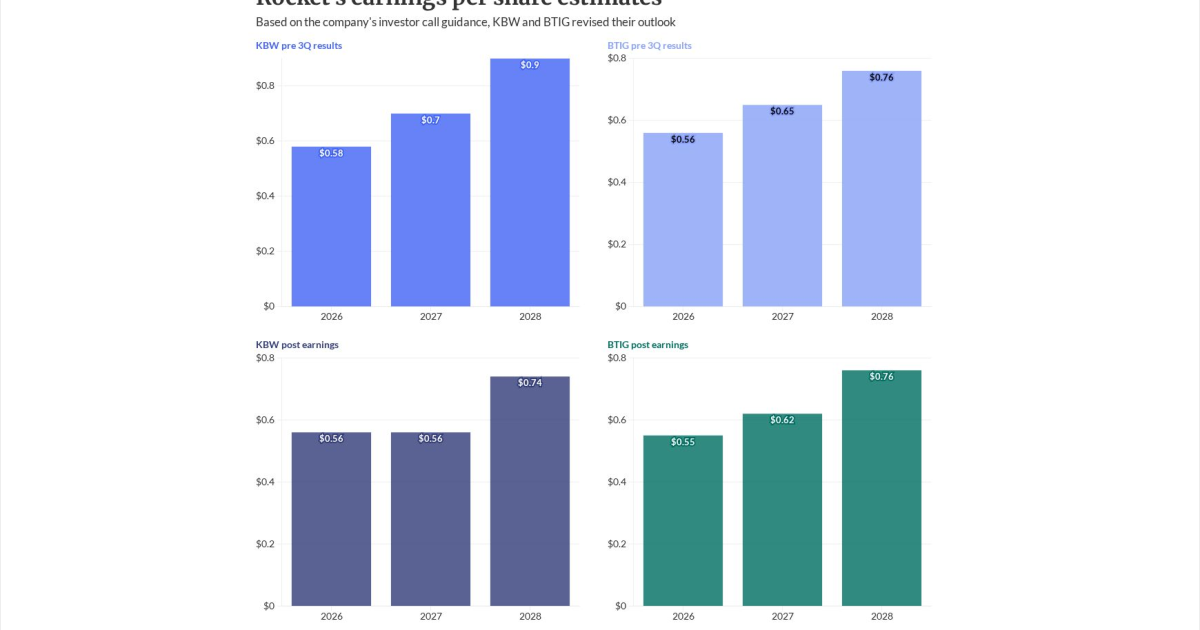
This led George to drop his full year earnings per share estimate for 2026 by 2 cents to 56 cents per share. But he made larger cuts over the next two years. For 2027, the new estimate is also 56 cents per share, but this compares with the previous 70 cents per share.
He dropped 2028 EPS to 74 cents per share from 90 cents.
BTIG's analysts also adjusted the earnings forecast at Rocket for this year and next, noting the "more challenging" mortgage market.
What BTIG sees happening with Rocket
Rocket's third quarter results and its guidance for the current period "exhibited both the relative strength and the limitations from a challenging mortgage environment; we think both factors are likely to continue over the near-term," said Douglas Harter of BTIG. "The lack of visibility into meaningful improvement in earnings power means the shares appear fairly valued and the quality of the franchise/level of execution limit the downside."
Harter cut the 2026 EPS forecast at Rocket by 1 cent, to 55 cents per share. For next year, the estimate was dropped by 3 cents, to 62 cents per share. But Harter left his 2028 estimate at 76 cents per share.
BTIG also decreased its origination volume estimates by 4%, 11% and 3% in 2026 through 2028 respectively, "given the persistence of higher mortgage rates," the report said.
What the analysts see for Rocket's volume
For this year, Rocket will end up with $172.8 billion of originations, but this is expected to fall to $156.8 billion in 2027, BTIG said. In 2025, Rocket did $130.4 billion; but it acquired
Combining with Mr. Cooper gave Rocket the industry's largest servicing portfolio and management keyed on the recapture potential it brings.
KBW is forecasting $173.6 billion this year, with $168 billion in 2027 and $200 billion the following year.
In his report, George said he expects 2027 volume of $1.86 trillion, "well below normalized levels, suggesting earnings upside over time as activity recovers."
The target price was reduced to $16 per share from $17 by KBW.
Harter dropped the gain on sale revenue forecast by 5% lower this year and 9% lower in 2027 as a result.
"This decline is partially offset by lower expenses as we expect Rocket to continue to reduce expenses in a lower volume environment," Harter said.
KBW expects Rocket to report gain on sale across all of its channels of 262 basis points for the full year. For both 2027 and 2028, George foresees 255 basis points each year. The BTIG report only gives numbers for this year and next, and its outlook is similar for gain on sale.
BTIG maintained its neutral rating on Rocket, while KBW kept the stock at outperform.
KBW downgrades PennyMac Financial
For PennyMac Financial Services, George downgraded the stock to market perform from outperform because of a "lack of near-term catalysts and weak trends."
Its share price is down 53% year-to-date and the trend "broadly reflects the current market backdrop and limited visibility into the path to double-digit return on equity," George said, in
"This was already a self-help story, but the macro backdrop adds another incremental headwind. So we are moving to the sidelines and downgrading to market perform."
Earnings estimates were dropped to $5.47 per share for 2026, $5.53 for 2027 and $7.91 for 2028 from $6.20, $8.86 and $10.95 respectively by KBW.
George dropped his target price to $80 per share from $100.
BTIG reiterated its buy rating, even with the pressure to Pennymac's return on equity. It viewed a $29 billion mortgage servicing rights sale (and use of proceeds to pay down debt) plus cost-cutting moves as positives.
BTIG sees an attractive risk/reward proposition
"The improvement in ROEs is still likely two-plus quarters away, but at the current valuation (74% of current book) we see the shares offering attractive risk/reward and reiterate our Buy rating," BTIG said.
But, it is still lowering its estimates to $5.58 from $5.96 in 2026; $5.80 from $6.30 next year; and $9.25 from $9.70 for the following year. "Our estimates assume PFSI's ROE remains in the mid-to-high single-digit range through the end of 2027 but surpasses 10% in 2028," Harter said.
But his estimates do not include any benefit Pennymac will get