Mortgage businesses must focus on customer outcomes, governance and end-to-end processes when adopting artificial intelligence (AI), industry leaders told delegates at MIT Live 2026.
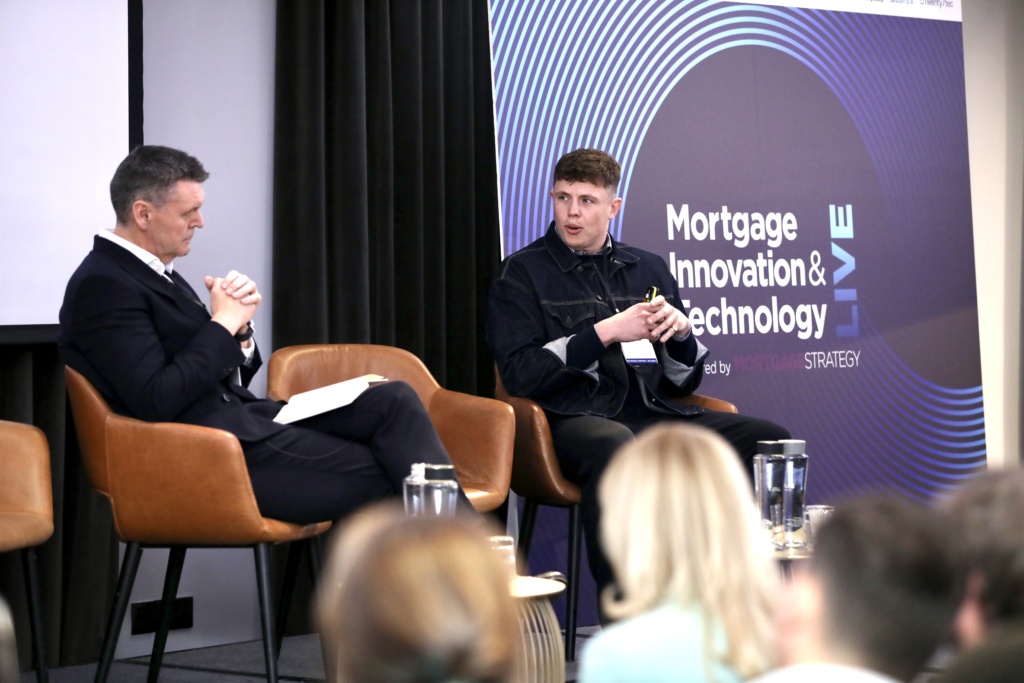
Speaking during a joint case study session, The Decision to Depend on AI, Jamie Lawless, co-founder and chief executive of LendWell, and Ken Murray, chief executive of Finance Solutions, part of Howden Group, explored the risks, results and practical lessons of using LendWell to update the systems of Finance Solutions.
The session examined how firms can move beyond AI experimentation to deliver business improvements while keeping security, compliance and control.
Lawless said that while many businesses had experienced the initial excitement of using AI, the focus needed to shift towards the tangible benefits it could deliver.
“We have all had that magical AI moment, but then the follow-on questions come,” he said. “How will this serve my customers? How will it meet my business needs? The business outcome is the brief, for technology.”
He also warned that businesses would struggle to realise the full benefits of AI if they continued to reward employees for working in the same ways they had before its introduction.
“If you incentivise your team to work in the old model, they will work in the old model,” Lawless said.
While AI was already delivering innovation in specific areas, including fact-finding, he argued that firms needed to look at its impact across the entire mortgage process rather than focusing on individual tasks in isolation.
“When you look at AI today there are very powerful pockets of innovation,” he said. “For example, the fact find. But you have to look at it over the purview of the entire process and what it gives back to the adviser.”
Murray pointed to the scale of transformation already taking place at Finance Solutions, citing 1.4 million documents moved as part of the work discussed during the session.
He stressed that technology should support the relationship between advisers and clients, arguing that maintaining that connection remained central.
Murray also suggested that technological transformation could return 52% of advisers’ time to them, creating an opportunity to focus more on higher-value activities and client relationships.
Offering advice to mortgage professionals looking to upgrade their technology, Murray urged firms to begin by mapping their processes from end to end and involving the people who understand them best.
“Map your processes end to end,” he said. “Speak to your key team, and get buy in from your key advisers. Pick your partner well. They have to be of the same personality as your own business.”