
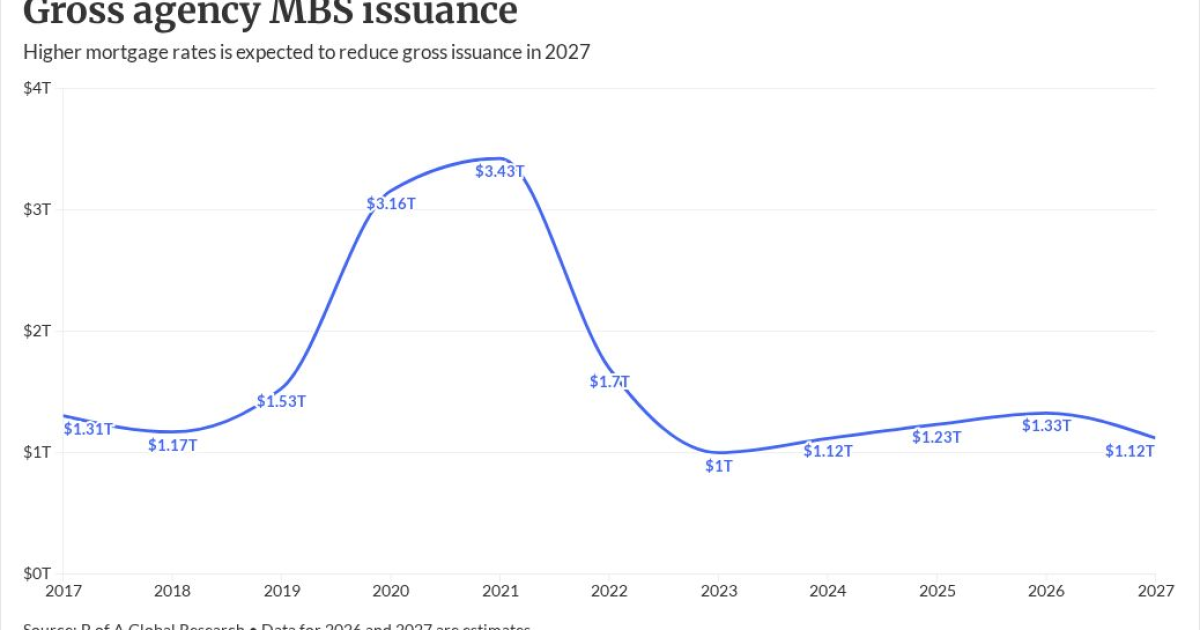
- Key Insight: See why Bank of America expects 2027 agency MBS issuances to drop by 16%.
- What's at Stake: Whether lenders can survive a grim market while investors benefit from lighter supply.
- Supporting Data: $1.12 trillion in projected gross MBS volume for 2027.
Agency securitization issuances are predicted to decline by 16% in 2027 on weaker home sales and more all-cash transactions due to persistently high mortgage rates, the latest Bank of America Securities weekly report said.
Gross MBS volume for next year of $1.12 trillion compares with B of A's latest forecast of $1.33 trillion during 2026, a slight upward revision from the previous prediction of $1.32 trillion for this year.
Its forecast is based on expectations that the 10-year Treasury yield will average 5.25%. Between Sept. 25 and Oct. 14, this had been close to or above this mark. But thanks to a rally at the end of the week, on Monday morning it opened at 5.09%.
Other inputs into the 2027 forecast included a 2.5% drop in existing home sales, a 0.5% gain in new home sales and 1% annual home price appreciation.
How B of A 2027 outlook compares with Fannie and MBA
Fannie Mae just reduced its
But the B of A analysts are more bearish for next year, and are now predicting $1.72 trillion of 2027 volume.
"We believe our numbers reflect our slightly more conservative view on housing and home sales and a marginally higher projected year-end rate level," the report said.
B of A prediction for total originations in 2026 is also slightly under both MBA and Fannie Mae's predictions, at $2.03 trillion.
A "grim" MBA Annual
"Light expected issuance was a theme at the MBA annual conference, where the tone from lenders was grim, but the light supply should be a positive technical for investors," said the report, which lists Jeana Curro as the lead analyst.
As for the 10-year, the analysts remain "secular bears," but the rally could bring yields to levels between 4.92% and 5.02%, "or potentially deeper but not to fall below 4.74%."
The conforming 30-year fixed rate mortgage averaged 7.458% at its most recent high point, on Oct. 4, according to data from Optimal Blue. Since then, the rate — except for Oct. 14, the day
Why net issuance will decline
B of A also predicted a 23% drop off in net issuance (takes into account mortgage pay downs, prepayments and pay-offs) in 2027. This is "driven primarily by
"These headwinds are expected to be partially offset by a modest increase in cash-out refinance activity and
The amount of agency-eligible investor loans going into non-agency issuances has grown since 2023, from $1.5 trillion to $10.1 trillion for last year and $12.4 trillion so far in 2026.
The 2026 total does not include $5.3 trillion of agency conforming loans which went into private-label securities, up from $2.7 trillion in 2025.
"We expect this strength to continue in to 2027, and estimate the corresponding reduction in Agency MBS net issuance at $25 billion," the report said.
A hold-out expecting an October FOMC hike
The B of A economists are also maintaining their prediction that the Federal Open Market Committee will raise short-term rates in October, but added it is "a close call," as the markets gave it a 25% probability when the report was written on Oct. 16.
On Monday morning, probabilities as measured by CME FedWatch were nearly 83% for no action and just 17.2% for a 25 basis point increase in the target.
This being said, the likelihood of a December hike was over 90%, CME FedWatch said.