

Four in 10 buy-to-let landlords will refinance at least one property in the next 12 months, according to Paragon Bank research.
The research, conducted by Pegasus Insight on Paragon’s behalf, surveyed almost 600 landlords.
It discovered that 38% of those with buy-to-let mortgages plan to either remortgage or switch to a new product with their existing lender over the coming year.
Those intending to refinance expect to deal with an average of 2.9 buy-to-let mortgages each.
The survey also revealed that 43% of landlords own all their rental properties outright, while 31% have a combination of mortgaged and unencumbered properties.
The remaining 26% have mortgages against all their rental properties.
Refinancing activity has become an increasingly important feature of the buy-to-let market as five-year fixed-rate mortgages taken out during the pandemic-era property boom reach maturity.
According to UK Finance, a record £18.2bn was lent for buy-to-let house purchases in 2021, followed by a further £17.4bn in 2022.
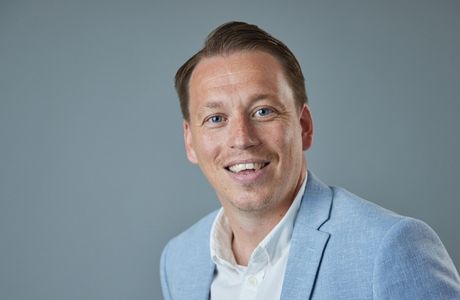
Louisa Sedgwick, managing director of mortgages at Paragon Bank, said remortgaging accounted for three-quarters of the lender’s buy-to-let business during the first half of 2026.
She expects refinancing to remain a major driver of activity, given the volume of lending completed in 2021 and 2022, when landlords took advantage of the Stamp Duty holiday.
“For brokers, that creates an opportunity to work with landlords ahead of upcoming maturities, looking across their portfolios at refinancing requirements as well as wider borrowing needs, such as releasing equity for property improvements or future investment,” she said.
Sedgwick added that brokers should consider landlords’ wider funding requirements rather than focusing solely on individual mortgage maturities.
This could involve raising capital against properties owned outright or releasing equity from existing investments to finance improvements and further acquisitions, subject to lending criteria and affordability.
She also highlighted the potential benefits of reviewing several mortgages together when landlords have multiple properties approaching the end of their fixed-rate terms.