
The Federal Housing Finance Agency's latest credit modernization moves mean loans originated only with newer credit scores could also show up in the private market, where Standard & Poor's analysts say they're ready for both VantageScore 4.0 and FICO 10T.
S&P found 4.0 and 10T "looked a lot more like each other than classic FICO" when examined, allowing for both to be similarly
The mapping adjusts for differences between score bands, with lower numbers for 4.0 and 10T aligning with higher FICOs. Alignment between older and newer measures occurred around 640, and there are deductions from the more modernized metrics above 647.
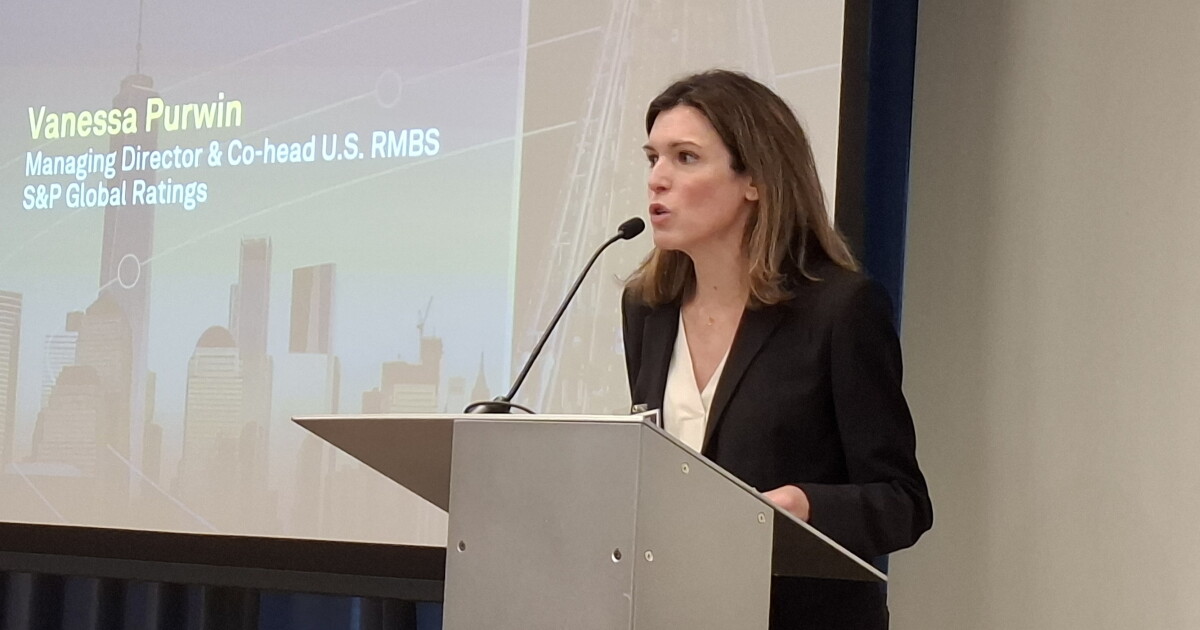
"Mortgage scoring is entering a new era, and our objective is to preserve the analytical foundations that the market depends on," Purwin told attendees at S&P's Americas Structured Finance Conference.
S&P will tweak modeled losses that could otherwise look artificially low to account for lender choice.
"Depending on the level of transparency and disclosure for a particular lender or a particular transaction, we may need to make additional adjustments to these mappings to appropriately account for the risk of bias," she said.
While the scores bring a variety of new characteristics to the table, Purwin said the shift from relying on a one-time view of consumers' payment histories to their patterns over time is the most influential.
"Trended credit data is really the largest advancement that we've seen in the residential mortgage market in decades," Purwin said.
Dynamic payment data boosts scores by 5-35 for repeat homebuyers with more history and 10-20 for those at entry level, she said.
Single-family mortgages originated with new scores have been put into private securitizations but these typically have been submitted alongside classic FICOs, requiring investment in two credit metrics.
S&P's rating universe has included second liens from originators that exclusively used a newer score, but classic FICOs were submitted at the time of securitization in that case, Jeremy Schneider, managing director and RMBS sector lead at S&P, said during a press Q&A session.
More developments in the GSE market
Recent FHFA moves that have accelerated the use of the 4.0 score in the neighboring government-sponsored enterprise MBS market have included the release of
FHFA Director Bill Pulte, who favors using social media to announce policy, initially released a purchase mortgage version of the grid in an X post. A more
The GSEs have released historical data for both 10T and VS4 as well as for its own internal scores to support legislatively-mandated credit modernization.
In response,
"More marketplace data and more comparative metrics will, down the road, be instrumental in stemming the recent annual skyrocketing of mortgage credit score prices," the CHLA wrote, while showing concern there could still be at least one FICO rate increase before that happens.
FICO stock price had rebounded and was up more than 11% on the day Thursday, recovering somewhat from a larger decline that followed the FHFA's latest credit scoring announcements as it fell to levels some buyers found attractive.
The share of VantageScore loans sold to the GSEs plateaued in September at 5.5%, but the number of lenders involved grew in line with the expansion of eligibility from a pilot involving large players to a broader rollout, according to Keefe, Bruyette & Woods.
Nonbank lending giants Rocket Mortgage and United Wholesale once again were the main sellers of VS4 loans but their combined share of this market dropped slightly from roughly 99% to around 95%.
Rocket sold 4,241 VS4 loans to the enterprises in September, followed by UWM with 984; Amerisave, 263; Pennymac, 45; and CrossCountry, 4. First State Bank, Plaza Home Mortgage, and ResiCentral each sold one VS4 loan to the GSEs during the month.
"Given the changes and the likely interest rate benefit for loans using VS4, we expect usage of VS4 to increase," Bose George, Frankie Labetti, and Graham Bundy, analysts at KBW, wrote.